The Elevator Receipt
Meta has $279 billion in data center leases waiting to start and is now planning to rent out the surplus capacity. On October 5, CME's futures on the GPU-hour are scheduled to start trading. Chicago ran this exact play on wheat in the 1850s, and the profits didn't go to the farmers.
On July 1, Bloomberg reported that Meta is building a cloud business to sell access to its spare AI compute, an initiative reportedly called Meta Compute. This is the same company that, as of June 30, had $279 billion in data center leases signed but not yet started (and signed another $68 billion in July), with an Ohio campus coming online this year and a Louisiana campus behind it, which Zuckerberg pitched as covering a significant part of the footprint of Manhattan. Zuckerberg had said in May that a cloud business was "definitely on the table." Meta was not even first.
In early May, the entire capacity of Colossus 1, the data center xAI built before it was folded into SpaceX, went to Anthropic in a buyout deal, followed by similar leases with Google and Reflection AI. In August, SpaceX reported that second-quarter revenue had nearly doubled, from $4 billion to $7.8 billion year over year, with compute deals contributing close to $2 billion of the growth, plus another $6.7 billion in cloud revenue under contract for a six-month stretch that starts ramping in October. The exchanges moved in the same window. On May 12, CME Group and Silicon Data announced the first compute futures market, built on daily GPU rental-rate indices, and days later ICE and Ornn announced cash-settled GPU compute futures on an index tracking live spot prices for H100s, H200s, and B200s. SF Compute already runs a live order book where GPU-hours trade like any commodity, and the spot price of a Blackwell GPU-hour rose 48 percent between mid-February and mid-April, from $2.75 to $4.08.
And on that ticker, CME has already set the date its first two contracts, H100 and B200 rental index futures, would start trading, pending regulatory review: October 5, 2026.
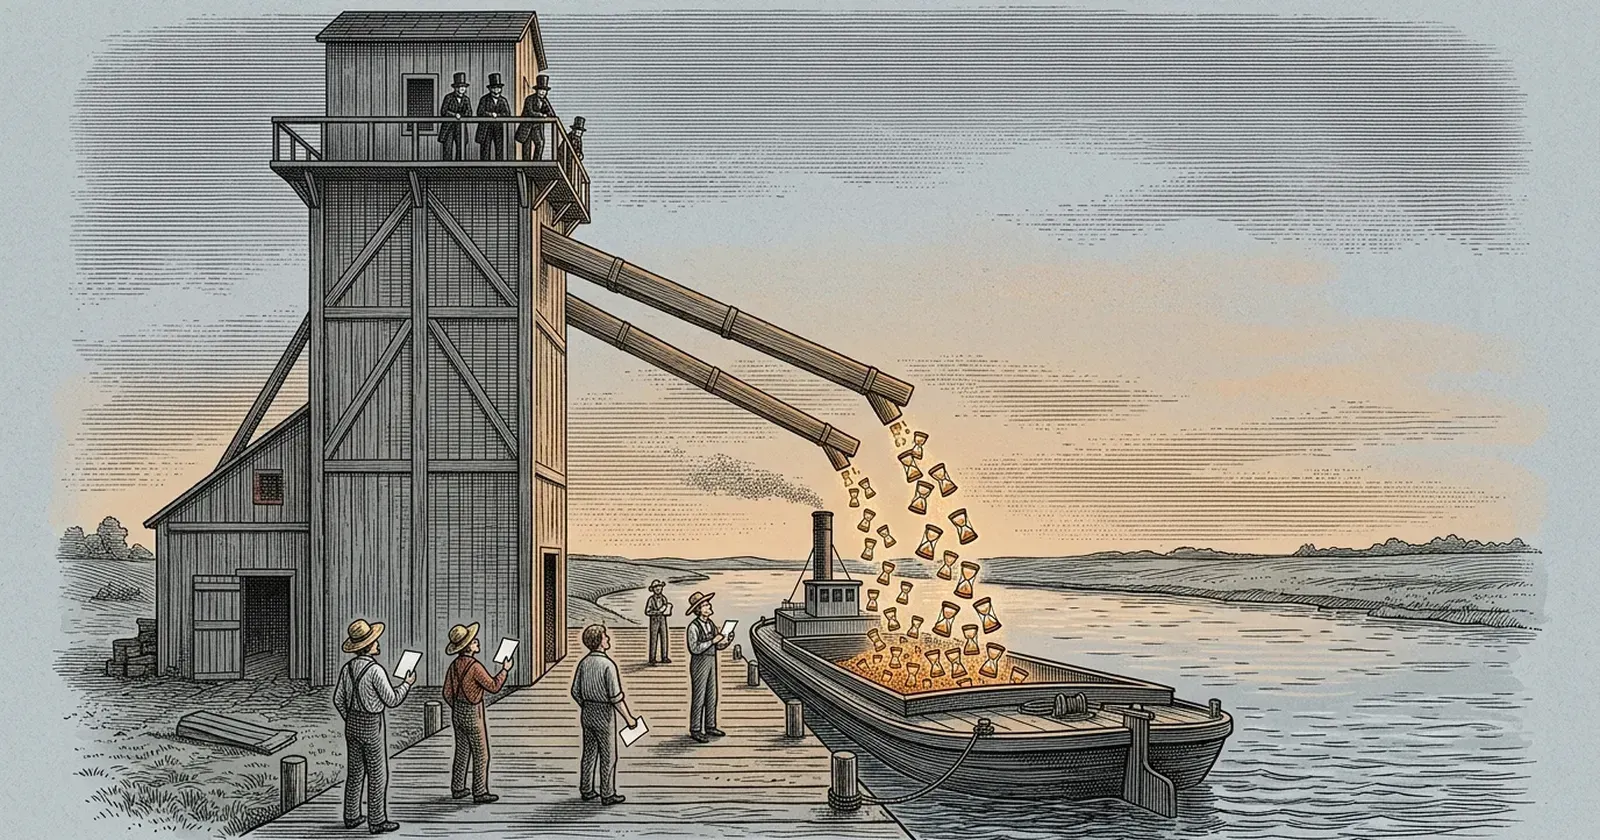
A bit of a detour to the history of commodities. Before the 1850s, American grain traveled in sacks. Each sack belonged to a specific farmer, was moved under his name, and was sold on inspection, so a farmer with better wheat than his neighbor got paid the difference. Joseph Dart opened the first steam-powered grain elevator in Buffalo in 1843, a machine that ran grain up a bucket conveyor into storage bins and unloaded lake boats several times faster than the crews who had needed days to empty one by hand. The Chicago Board of Trade began grading wheat in 1856, sorting everything that came through into categories: No. 1 spring, No. 2 spring, and so on down the list. Once graded, a farmer's wheat went up the elevator leg and blended into a bin with every other load that met the same grade, and what the farmer carried away was a paper receipt for so many bushels of No. 2. Receipts could be sold without moving the grain. Then they could be sold before the grain existed, and in 1865 the Board formalized the practice into futures contracts.
Within a generation, Chicago was clearing trades on wheat that had not yet been harvested, and the farmers were organizing a national political movement, the Grangers, aimed in large part at the elevator operators and the railroads that fed them. In 1877, the Supreme Court upheld state regulation of elevator rates in Munn v. Illinois by dusting off a phrase from a seventeenth-century English judge, "business affected with a public interest," to address the fact that a handful of warehousemen had become the chokepoint for the national harvest. William Cronon's Nature's Metropolis tells the full story, and it remains the best systems book I know, even though it's technically about corn.
Two things happened when wheat became fungible. Liquidity exploded, which was good for nearly everyone. AND power moved away from the people who grew the wheat and toward the people who ran the elevators, defined the grades, and cleared the trades. The farmer gained a global market and lost every ounce of pricing power that came from his wheat being his.
I think this is happening again. The exchanges are building the grading system, and Meta just volunteered to pour its harvest into the bin. Bloomberg says Meta may sell "raw" capacity the way CoreWeave does, which is an admission, stated in infrastructure rather than words, that an H100-hour in Meta's Ohio campus is interchangeable with an H100-hour anywhere else. And remember the story that justified the capex in the first place: our compute trains our models; our models power our products; the flywheel compounds; none of it is for sale. Meta AI and Llama still do not appear as a revenue line anywhere, and the company has now conceded the first link in the flywheel by renting it out. (Zuckerberg's version, on the July earnings call, is that selling intelligence carries "a significantly higher margin" than selling compute, and that it "would be foolish to basically just sell all of the compute." He also said buyers are already offering "a meaningful premium" over what Meta paid for it.) The megawatt turned out to be the crop. The models were supposed to be milled flour, and there does not appear to be enough demand for it.
I don't think selling the surplus is a mistake, to be clear. Pretending your commodity is a moat costs money and adds extra steps. (And before anyone emails me: no, AWS was not built from Amazon's spare holiday capacity. That story is a myth Amazon's own engineers have spent fifteen years trying to kill. AWS was a deliberate business from day one, which is exactly the point. Companies that win infrastructure markets decide to be infrastructure companies; they don't back into it.)
But the history is blunt about who captures the profits in a commodity market, and it is not the growers. It is whoever defines the grade, runs the elevator, and clears the trade. In compute terms: the index publishers, the exchanges, the interconnects, and above all, whoever controls where a workload can physically run. A futures market only helps you if you can take delivery, and taking delivery of compute means your workload can actually move to where the cheap capacity is. If your pipeline is welded to one region of one provider, the spot market is a spectator sport, and you get to watch the price of the thing you are overpaying for fall in real time. Fungibility is a property of your architecture, and most architectures I see were built on the assumption that compute would never be worth arbitraging.
Nobody in Chicago planned to become the chokepoint for the American harvest either. They just printed the receipts.
Want to learn how intelligent data pipelines can reduce your AI costs? Check out Expanso. Or don't. Who am I to tell you what to do?
NOTE: I'm currently writing a book based on what I have seen about the real-world challenges of data preparation for machine learning, focusing on operational, compliance, and cost. I'd love to hear your thoughts!